

When Your Premium Passes $100,000
Past six figures of premium you stop choosing a carrier and start choosing a structure. Here is what actually changes, including several Michigan rules almost nobody quotes correctly.
Read article →Michigan-specific insurance education, news, and practical advice from our team of licensed agents. Updated regularly.
Past six figures of premium you stop choosing a carrier and start choosing a structure. Here is what actually changes, including several Michigan rules almost nobody quotes correctly.
Read article →
Your defense lawyer is paid out of your limit. Switching carriers can erase a decade of prior acts. And Michigan's statutes hand CPA firms a real shield that most of them give away in the engagement letter.
Read article →
Your malpractice policy covers you. It usually excludes the corporation you practice through, and your general liability was endorsed to exclude the negligent-supervision claim that reaches it.
Read article →
The tooling on your floor usually belongs to your customer, and the standard property form gives it $2,500. That is one of four places a plastics program quietly fails.
Read article →
Michigan courts have enforced alarm contract liability caps. That is genuinely good news, and it is also the reason so many alarm companies are underinsured for the claim that actually lands.
Read article →
Fair housing claims, double security-deposit damages and a new assault and battery exclusion. Three of an apartment owner's real exposures sit outside the policy most owners think covers them.
Read article →
Every car in your bays is excluded by your general liability policy three different ways. Garagekeepers is the fix, and which of its three versions you own changes everything.
Read article →
A Michigan manufacturer with an approved tasting room is not a retail licensee for most of the Liquor Control Code. It is one for dram shop, for the $50,000 filing, and for server training.
Read article →
Carry three quarters of what your coinsurance clause requires and you pay a quarter of every partial loss yourself. Here is how coinsurance, vacancy and ordinance coverage really work.
Read article →
Michigan's Condominium Act does not draw the walls-in line and does not order an association to buy insurance. Your master deed does the first job and an administrative rule does the second.
Read article →
Most electrical contractors carry the right limits and still fail the contract. Here is what additional insured, waiver of subrogation and completed operations really mean on a Michigan job.
Read article →
Michigan's dig notice is 72 hours, not three working days, and on the standard liability form underground damage is covered unless somebody endorsed it away. Both are widely reported backwards.
Read article →
Michigan lets a family recover for mishandling of a body without proving any physical injury. A general liability policy insures bodily injury. Those two sentences do not line up.
Read article →
Michigan's leading health club waiver case is one the gym lost, because its release never told the member he was giving up the right to sue. And a parent cannot waive a child's claim at all.
Read article →
Refrigerant and carbon monoxide are pollutants under a standard liability policy. Here is what that means for a Michigan mechanical contractor, and the endorsement to look for first.
Read article →
A general liability policy will not pay to recall your customer's parts, and a property policy will not pay when the machine itself fails. Here is how a real Michigan machine shop program is built.
Read article →
A joint your tech soldered Tuesday lets go Saturday. Your liability policy is generally built to make the homeowner whole and not to pay you to redo the joint. Here is where that line falls.
Read article →
The part of a liability policy that looks like it was written for an advertising agency is the part the form switches off for advertising agencies. Here is what actually answers the exposure.
Read article →
Michigan requires $50,000 of proof of financial responsibility to hold a liquor license. The Dram Shop Act sets a damages floor and no ceiling. Those two facts do not fit together.
Read article →
Michigan wrote the bailee question into statute, with an exception covering exactly the moments a claim arises. Know which side of it you are standing on.
Read article →
You did not manufacture it, but you get sued anyway. Here is how Michigan's seller statute, stock value reporting and cargo coverage fit together for a distributor.
Read article →
A parent cannot waive a minor's claim in Michigan. For a facility whose customers are almost entirely children, that changes what is actually protecting you.
Read article →
A percentage deductible is a percentage of your dwelling limit, not your claim — which is why 1% can mean $3,500. Here's how the math works, why it is happening, and the roof-settlement change that matters even more.
Read article →
Michigan gives new residents no grace period, will not accept your old state's policy to register a car, and runs a no-fault system that works nothing like where you came from. Here's the order to do things in.
Read article →
The breed rule protects you less than you have been told, a net and a locked gate are the price of keeping a trampoline, and for insurance purposes a pool needs a fence. What carriers actually do.
Read article →
A 1099 proves nothing. Michigan law can make you responsible for an uninsured sub's injured employee, charge their whole contract price to your policy at audit, and hold your LLC's managers personally liable.
Read article →
Usually not — but the reason is not an income threshold. It's that current forms exclude home-sharing by name, that 'occasional' will not stretch to a year-round listing, and that several property exclusions never mention income at all.
Read article →
Household staff workers comp, personal cyber fraud, a nonprofit board seat, excess uninsured motorist, the boat, the trust that owns the cottage — eight exposures a standard policy quietly leaves open.
Read article →
Published Michigan averages range from about $1,600 to $3,800 a year for full coverage. Here's why the estimates disagree, what actually drives your rate, and which levers you control.
Read article →
Six PIP medical choices, six different sets of eligibility rules, and savings that range from 3.6% to 88%. Here's what each level really costs you — and the $14 rider almost nobody buys.
Read article →
Michigan does not require a surety bond for a builder license — but public projects over $50,000 and a lot of city permits do. Here's which bonds you actually need, what they cost, and why a bond is not insurance.
Read article →
Before you drop your PIP limit, understand what your health plan and Medicare will and won't do — annual deductibles that reset every January, dental caps that haven't moved in decades, and no coverage at all for in-home attendant care.
Read article →
Almost certainly not. Standard Michigan auto policies exclude carrying property for a fee, and DoorDash's own coverage explicitly does not repair your car. Here's the gap and the two ways to close it.
Read article →
Michigan's civil rights law applies to employers with one employee — not fifteen — and it has no cap on compensatory damages. That combination makes EPLI more relevant to small Michigan employers than it is in most states.
Read article →
Property insurance rebuilds the building. Business interruption insurance is what keeps the lights on, payroll met, and the doors reopening. Here's how the coverage actually works in Michigan — and the four settings that decide whether it pays enough.
Read article →
Three words that sound interchangeable and settle claims completely differently. If your classic is on a standard auto policy, a total loss pays depreciated book value — which for a restored car is a disaster.
Read article →
Your association's master policy insures the building. It almost never insures your floors, cabinets, or belongings — and in Michigan it can hand you the deductible too. Here's what an HO-6 policy is for and how to size it.
Read article →
A seasonal place empty from November to May is a different risk than the house you live in — and it's usually insured as if it weren't. Vacancy clauses, frozen pipes, docks, and rental use are where cottage claims go wrong.
Read article →
Your homeowners policy has a special limit on jewelry theft — often around $1,500 total, not per item. Scheduling the piece removes that cap, broadens the perils, and usually costs less than people expect.
Read article →
A certificate of insurance proves you have coverage. It does not give the person holding it any coverage. Understanding that one distinction is what separates businesses that are actually protected from businesses that just have paperwork.
Read article →
Your class code is the single biggest driver of what workers' comp costs — and Michigan doesn't use the national NCCI system that most guidance online assumes. Here's how Michigan classification actually works and how a wrong code costs you money.
Read article →
Michigan parents need 8–10x annual income in life insurance. Term life is cheaper and covers your family's critical years; whole life is permanent but pricier. Here's how to pick.
Read article →
Michigan contractors must carry workers' compensation, general liability, and auto insurance. Here's what the law requires, what protects your business, and what clients demand.
Read article →
Electric vehicles require the same liability coverage as gas cars in Michigan, but Teslas have unique risks. Here's what every Michigan Tesla owner needs to carry and why.
Read article →
Collision covers your car when you hit something; comprehensive covers almost everything else — theft, deer, hail, and glass. Here's how the two differ and which you need in Michigan.
Read article →
A cracked windshield is a comprehensive claim in Michigan — covered if you carry comprehensive coverage. Here's how the deductible works, why Michigan has no free-windshield law, and when to repair vs. replace.
Read article →
Homeowners insurance usually covers dog bite liability in Michigan — where owners face strict liability. Here's how the coverage works, breed exclusions to watch for, and why an umbrella matters.
Read article →
A burst pipe is usually covered by Michigan homeowners insurance — but only if you kept the heat on and maintained the home. Here's what's covered, what isn't, and how to avoid a denied claim.
Read article →
Michigan homeowners insurance covers a roof damaged by a sudden event like wind, hail, or a fallen tree — but not one that simply wore out. Here's what decides a covered claim, and RCV vs. ACV.
Read article →
Uninsured and underinsured motorist coverage protects you when an at-fault driver has no insurance or too little. It's optional in Michigan — here's why so many drivers add it anyway.
Read article →
A standard Michigan homeowners policy does NOT cover water backup or sump pump failure — you need a specific endorsement. Here's what it costs and how much to buy.
Read article →
Canadian wildfire smoke has Michigan homeowners asking if it's covered. For most, the honest answer is probably not — haze isn't physical damage, and your deductible eats the rest.
Read article →
Hitting a deer in Michigan is covered by comprehensive coverage — not collision. Here's how the claim works, what swerving changes, and what to do at the scene.
Read article →
Michigan's mini-tort lets you recover up to $3,000 in vehicle damage from an at-fault driver — including your collision deductible. Here's exactly how it works.
Read article →
If you own a higher-value home in Michigan, a standard homeowners policy can leave real gaps. Here's what those policies miss — and the coverage a well-appointed home actually needs.
Read article →
Commercial insurance rates aren't fixed — underwriters reward the businesses that manage risk well. Here are the levers that earn Michigan companies a lower rate.
Read article →
Insurers sort customers into preferred, standard, and non-standard tiers — and preferred pays the least. Here's what 'preferred' means in Michigan and how to qualify for the best rate.
Read article →Your experience modification rate quietly multiplies your Michigan workers' comp premium up or down. Here's how the EMR is calculated, how claims affect it, and how to lower it.
Read article →
Bundling your home and auto with one carrier can cut your total premium 10-25% in Michigan — but it isn't always the cheapest setup. Here's how the discount really works, what it's worth, and when splitting your policies wins.
Read article →
Forming an LLC protects your personal assets — but it doesn't pay claims, cover your equipment, or stop a lawsuit. Here's why Michigan LLCs and sole proprietors still need business insurance, and which coverages actually matter.
Read article →
Running a business from your Michigan home? Your homeowners policy barely covers it. Here's where the gaps are and the affordable coverage options that close them.
Read article →Renting out a property in Michigan? Your homeowners policy won't cover it. Here's what landlord insurance covers, what it costs, and the gaps that catch new landlords off guard.
Read article →
Pole barns, detached garages, and outbuildings are everywhere in Michigan — but your home policy may not cover yours the way you think. Here's how 'other structures' coverage works, where it falls short, and how to make sure your barn is actually protected.
Read article →
Adding a teen driver to your Michigan auto policy in 2026 — why it's so expensive here, the real dollar increase to expect, and the moves that actually bring the premium down.
Read article →
Closing on a Michigan home? Here's the insurance checklist — what your lender requires, what to line up before closing, the coverages buyers forget, and how to avoid paying too much from day one.
Read article →
A non-renewal or cancellation notice in Michigan isn't an emergency — but you do need to act before the deadline. Here's what it means, why it happens, and the exact steps to get re-covered without a lapse.
Read article →
What Michigan business insurance actually costs in 2026 — typical price ranges by coverage and industry, the factors that move your premium, and how to pay less without cutting protection.
Read article →
Thinking about switching insurance agents in Michigan? Here's exactly how it works — what you keep, what you don't have to do, and why it costs you nothing to switch agents without changing your coverage.
Read article →What cannabis and dispensary insurance costs in Michigan in 2026 — the coverage the state requires, typical price ranges for general liability and a full package, and what moves your premium.
Read article →
What workers' compensation actually costs a Michigan business in 2026 — how it's priced per $100 of payroll, why Michigan is one of the cheapest states, and the levers that decide whether you overpay.
Read article →
Launching a Michigan business? Here's the insurance you actually need on day one versus what can wait — what's legally required, what your clients and landlord will demand, and how to start lean without leaving a gap.
Read article →
Wind, hail, fallen trees, and power surges drive nearly half of all Michigan home insurance claims. Here's what your homeowners policy covers after a summer storm, what it doesn't, and the steps to take before and after the damage.
Read article →
Michigan homeowners: here's exactly how to file a home insurance claim step by step -- from documenting damage to getting your check.
Read article →
Michigan boat insurance starts at $200/year. RV insurance from $180/year. Learn what's required, what's covered, and when your home policy won't protect you.
Read article →
Michigan renters insurance averages $18/month and covers your belongings, liability, and hotel costs if your unit becomes uninhabitable.
Read article →
Using your personal vehicle for work in Michigan? Your personal policy may not cover you. Learn when you need commercial auto coverage.
Read article →
Only 17% of Michigan SMBs carry cyber insurance -- yet the average breach costs $200K+. Learn what cyber coverage includes and whether your business needs it.
Read article →
Michigan contractors: most GCs require $1M-$2M liability before you step on a job site. Here's what you need, what it costs, and how to get it fast.
Read article →
How much life insurance do you need in Michigan? Use the DIME method, 10x income rule, and our agent-tested checklist to find the right coverage amount.
Read article →A BOP bundles GL and property coverage for Michigan small businesses. Learn what it covers, what it doesn't, and what a policy costs in Michigan.
Read article →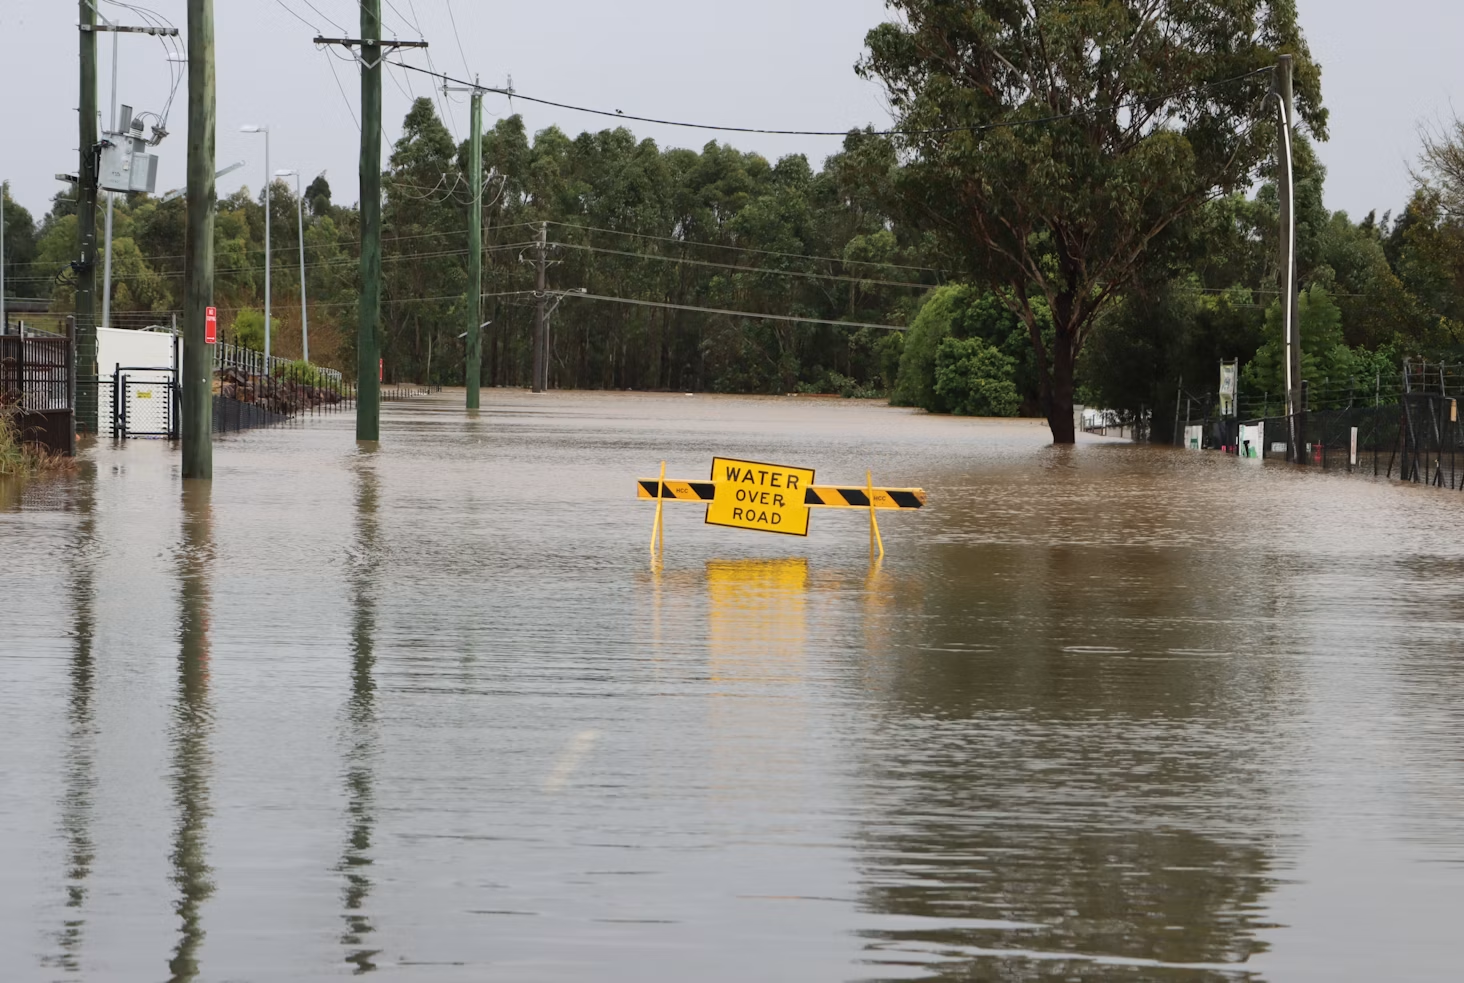
Homeowners insurance doesn't cover flood damage in Michigan. Learn what NFIP and private flood policies cover, what they cost, and who really needs one.
Read article →
Gap insurance in Michigan covers what's owed on your loan vs. your car's value after a total loss. Learn when you need it and what it costs.
Read article →
Adding a teen driver in Michigan raises your auto insurance by $2,500+ per year. Here's how to minimize the cost without cutting essential coverage.
Read article →
Michigan umbrella insurance costs $400-$600/year for $1M in coverage. Find out who needs it, what it covers, and what it doesn't.
Read article →
Term vs. whole life insurance in Michigan: a clear breakdown of cost, coverage length, cash value, and which one fits your family's needs.
Read article →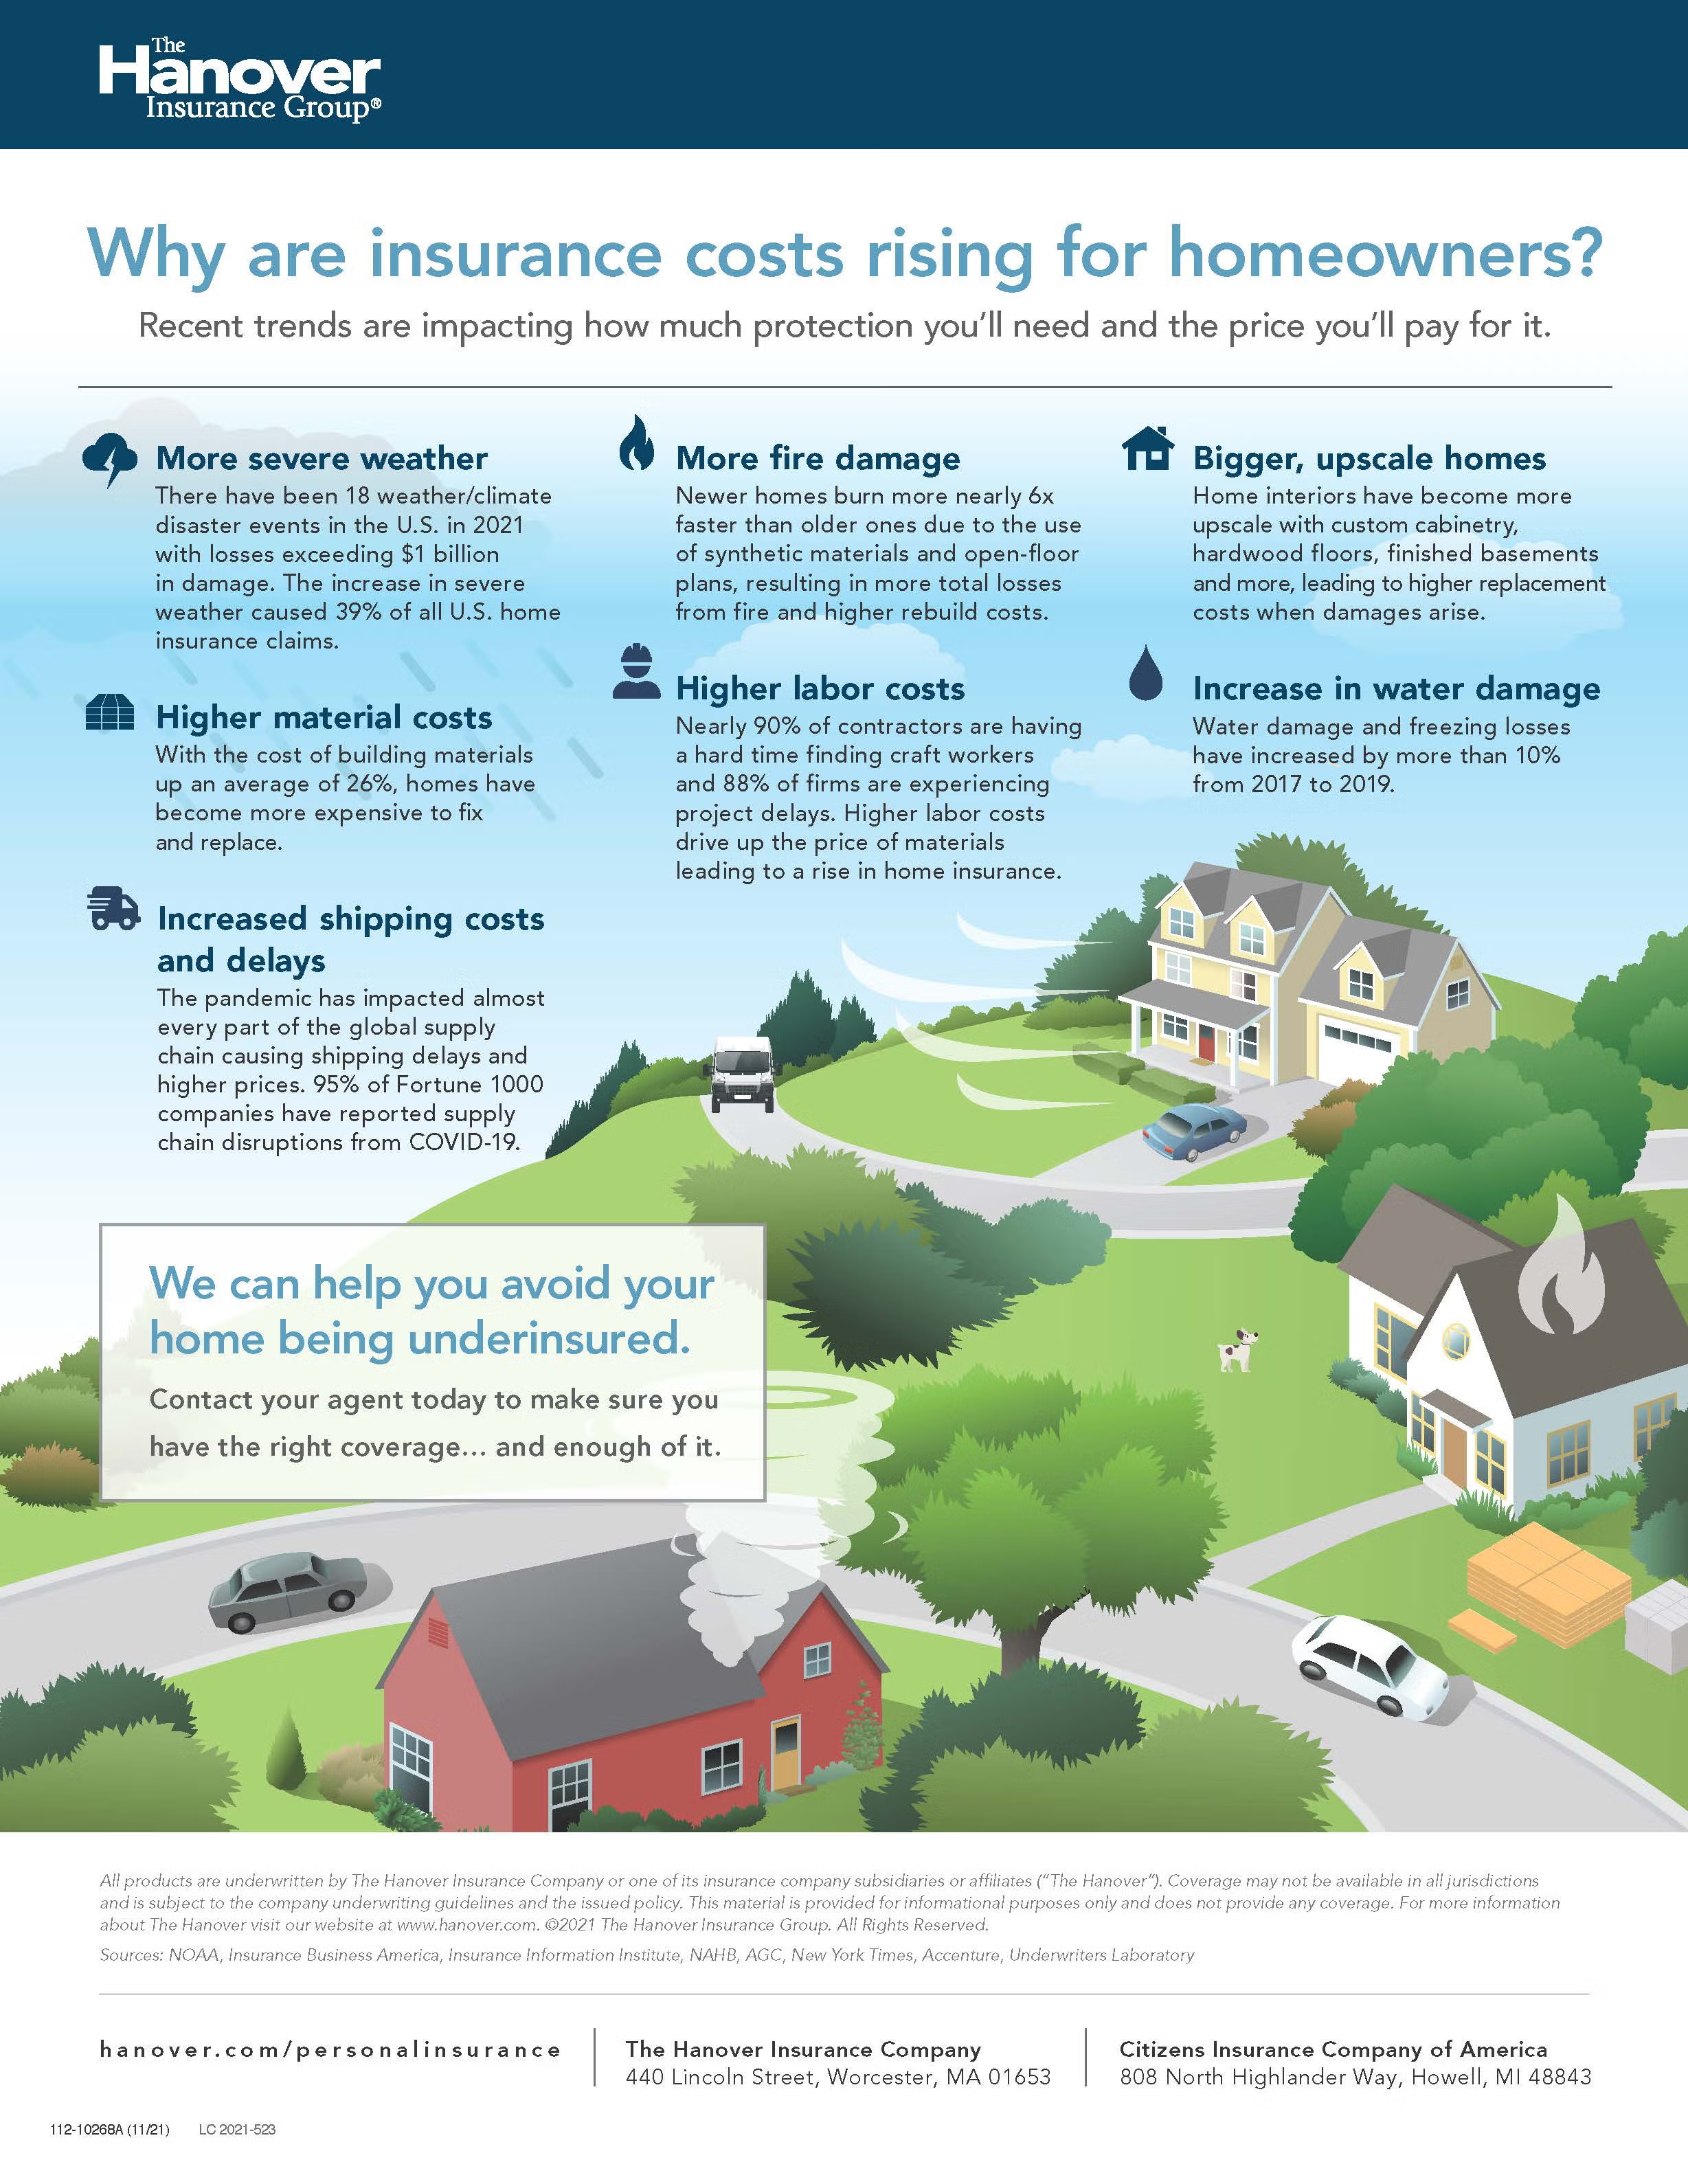
Michigan home insurance rates are up 21% over two years. Learn the real reasons your premium rose in 2026 and 7 proven ways to lower it.
Read article →
One call to JJA Insurance compares 10+ Michigan carriers. See why independent agents consistently beat captive agents on price and coverage options.
Read article →Every key auto insurance term defined — from Michigan's unique no-fault PIP tiers and liability minimums to physical damage coverage, endorsements, and underwriting concepts.
Read article →Every homeowners insurance term explained — policy forms HO-1 through HO-8, Coverage A through F, valuation methods, exclusions, endorsements, and Michigan-specific policy conditions.
Read article →
Real answers from Michigan-licensed agents — on no-fault PIP, flood coverage, deer strikes, gap insurance, umbrella policies, and more.
Read article →
Michigan motorcycle insurance terms explained — lay-up policies, agreed value, CPE coverage, guest passenger liability, and no-fault rules. Updated for 2025 Michigan law.
Read article →
Choosing Option 6 to use Medicare instead of PIP in Michigan? Explore the risks, coverage gaps, and potential out-of-pocket costs before you decide.
Read article →
Avoid severe penalties for a missed workers' comp audit in Michigan. Learn about the financial, legal, and insurance consequences for Michigan business owners.
Read article →Is workers' comp required for your small business in Michigan? Learn the criteria for mandatory coverage, exemptions, and the risks of non-compliance.
Read article →
Navigating your auto insurance policy can be confusing — especially with Michigan's no-fault system. This guide explains deductibles, liability, and PIP coverage in plain language.
Read article →
Most venues require proof of event insurance to use their space. Even at home, your Homeowners may not cover certain events. Here's why you need event coverage.
Read article →Get a free comparison quote across our 20+ carriers -- no obligation.
Start My Quote